5682 This document is effective from 1 January 2027 to accompany PS1/26.
5683Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
5684 PRA2026/1
5686 6. An institution shall, for the purpose of point (b) of paragraph 5 where collateral reflected in the
5687 calculation of ∗ is held against multiple facilities, comply with the requirements set out in
5688 LGD
5689 paragraph 7 of Credit Risk Mitigation (CRR) Part Article 193.
5690 [Note: This rule corresponds to Article 161 of CRR as it applied immediately before revocation by the
5691 Treasury]
5692 Article 162 MATURITY: CORPORATES AND INSTITUTIONS
5694 1. [Note: Provision left blank]
5695 2. An institution that uses the Foundation IRB Approach or the Advanced IRB Approach for
5696 exposures to corporates and institutions pursuant to Article 147A shall calculate M for each of
5697 these exposures in accordance with the calculation methods set out in paragraph 2A, subject to
5698 paragraph 3, provided that M shall be no greater than five years except in the cases specified in
5699 Credit Valuation Adjustment Risk Part 4.3 where M as specified there shall be used. Where an
5700 exposure falls within more than one point in paragraph 2A, the institution shall calculate M as
5701 follows:
5702 (a) where an exposure falls within both points (g) or (h) and any of (b), (c), (d) or (da) of
5703 paragraph 2A, it shall calculate M in accordance with point (g) or (h) of paragraph 2A as
5704 applicable;
5705 (b) where an exposure falls within both points (b) and (c) of paragraph 2A, it shall calculate M in
5706 accordance with point (c) of paragraph 2A; and
5707 (c) where an exposure falls within both points (a) and (k) of paragraph 2A, it shall calculate M in
5708 accordance with point (k) of paragraph 2A.
5709 2A.
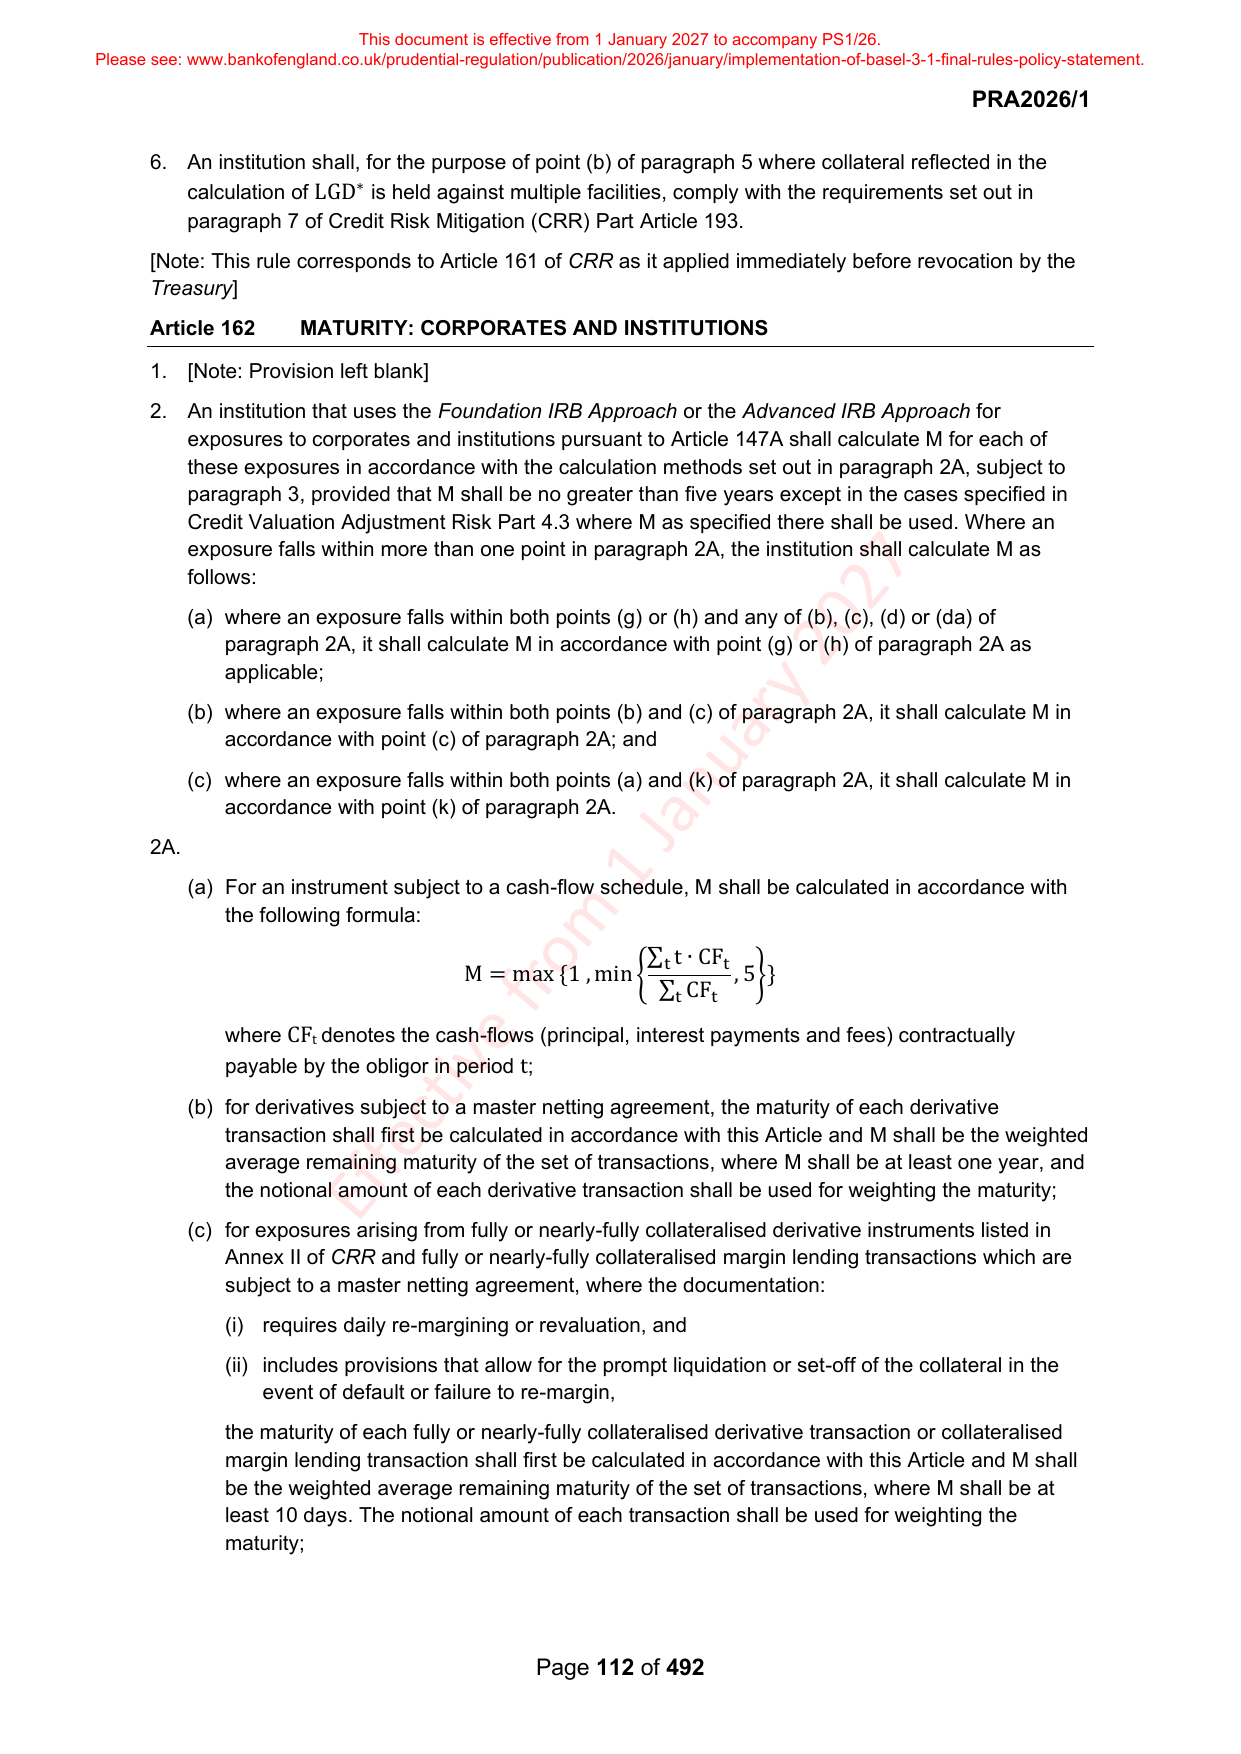
5710 (a) For an instrument subject to a cash-flow schedule, M shall be calculated in accordance with
5711 the following formula:
5713 ∑ t t ∙ CF t
5714 M = max {1 , min { , 5}}
5715 ∑ t CF t
5716 where CF t denotes the cash-flows (principal, interest payments and fees) contractually
5717 payable by the obligor in period t ;
5718 (b) for derivatives subject to a master netting agreement, the maturity of each derivative
5719 transaction shall first be calculated in accordance with this Article and M shall be the weighted
5720 average remaining maturity of the set of transactions, where M shall be at least one year, and
5721 the notional amount of each derivative transaction shall be used for weighting the maturity;
5722 (c) for exposures arising from fully or nearly-fully collateralised derivative instruments listed in
5723 Annex II of CRR and fully or nearly-fully collateralised margin lending transactions which are
5724 subject to a master netting agreement, where the documentation:
5725 (i) requires daily re-margining or revaluation, and
5726 (ii) includes provisions that allow for the prompt liquidation or set-off of the collateral in the
5727 event of default or failure to re-margin,
5728 the maturity of each fully or nearly-fully collateralised derivative transaction or collateralised
5729 margin lending transaction shall first be calculated in accordance with this Article and M shall
5730 be the weighted average remaining maturity of the set of transactions, where M shall be at
5731 least 10 days. The notional amount of each transaction shall be used for weighting the
5732 maturity;
5734 Page 112 of 492