5323 This document is effective from 1 January 2027 to accompany PS1/26.
5324Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
5325 PRA2026/1
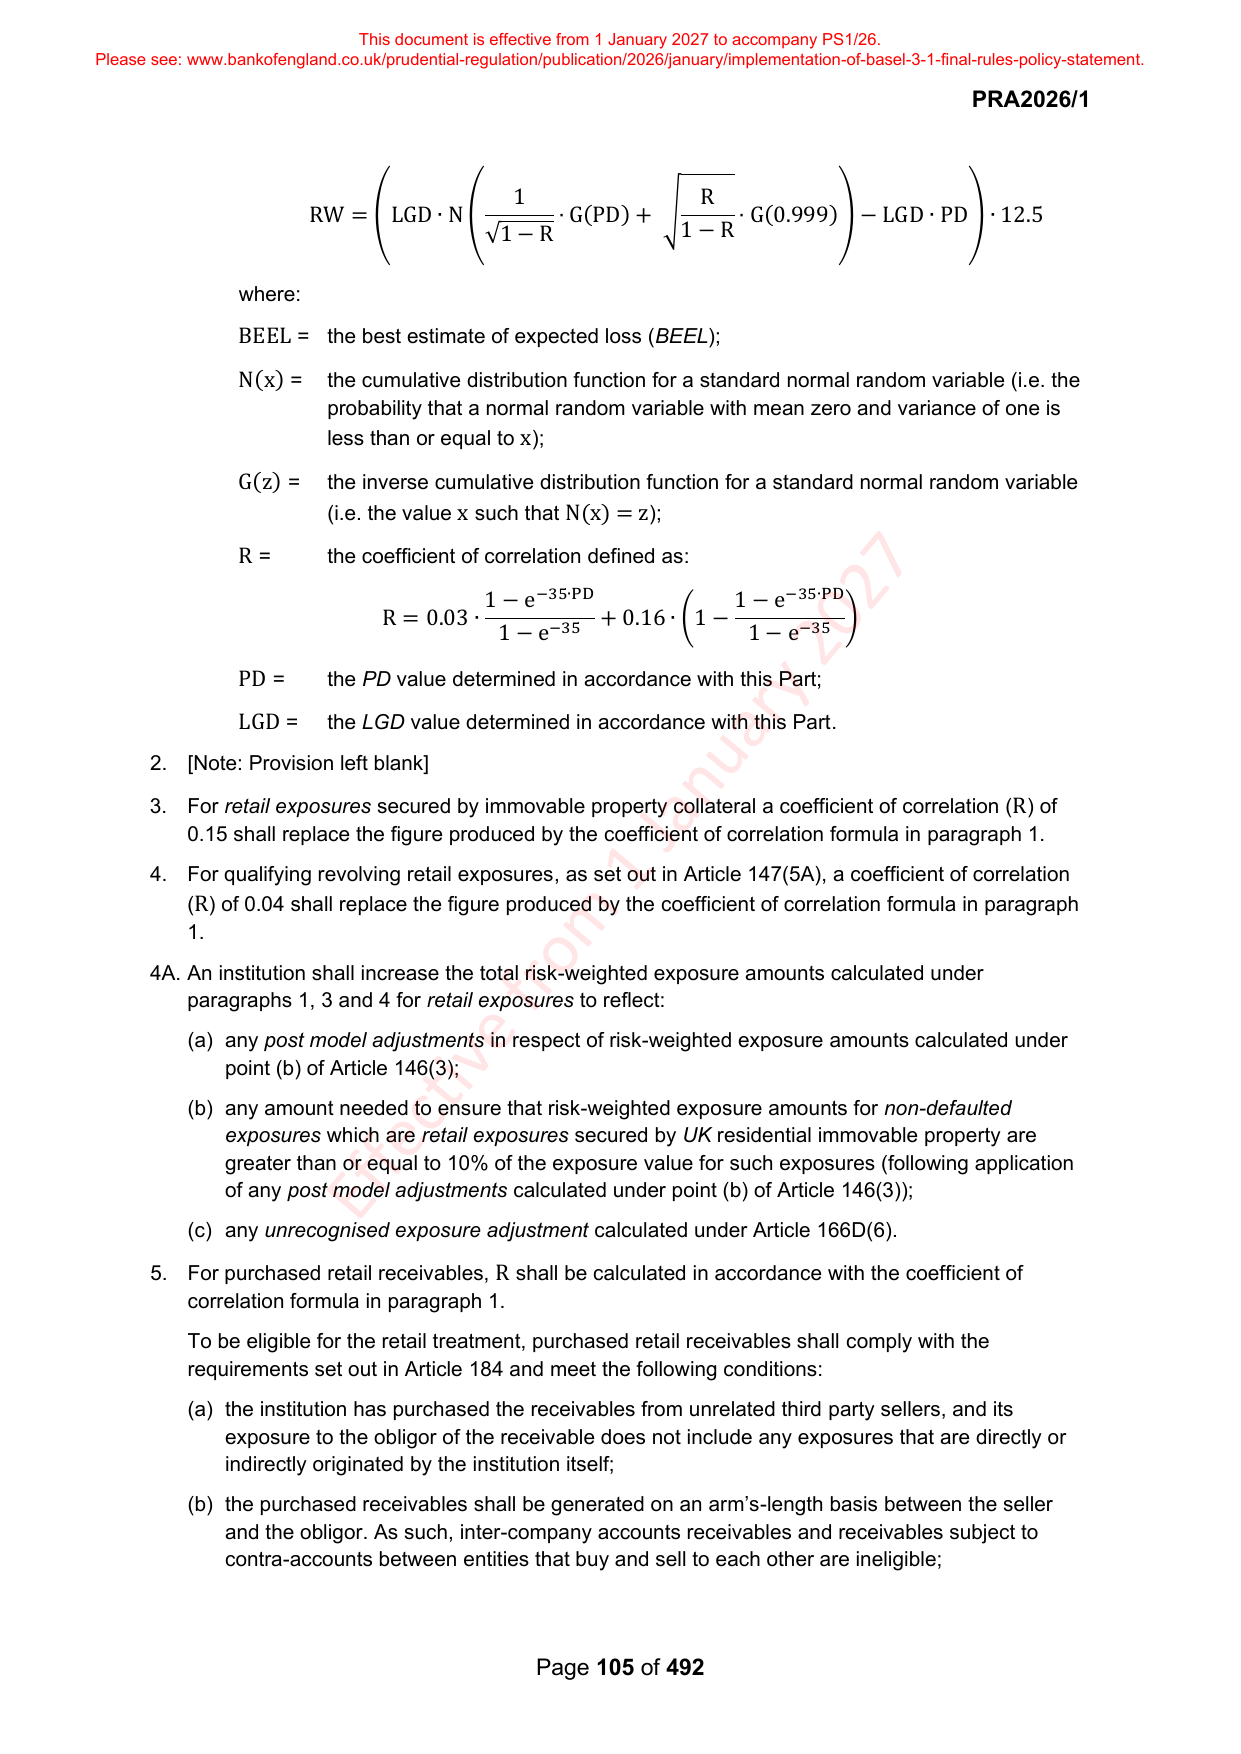
5327 1 R
5328 RW = (LGD ∙ N ( ∙ G(PD) + √ ∙ G(0.999)) − LGD ∙ PD) ∙ 12.5
5329 √1 − R 1−R
5331 where:
5333 BEEL = the best estimate of expected loss (BEEL);
5335 N(x) = the cumulative distribution function for a standard normal random variable (i.e. the
5336 probability that a normal random variable with mean zero and variance of one is
5337 less than or equal to x );
5339 G(z) = the inverse cumulative distribution function for a standard normal random variable
5340 (i.e. the value x such that N(x) = z );
5342 R = the coefficient of correlation defined as:
5343 −35∙PD −35∙PD
5344 1 − e 1 − e
5345 R = 0.03 ∙ + 0.16 ∙ (1 − )
5346 1 − e −35 1 − e −35
5348 PD = the PD value determined in accordance with this Part;
5350 LGD = the LGD value determined in accordance with this Part.
5351 2. [Note: Provision left blank]
5353 3. For retail exposures secured by immovable property collateral a coefficient of correlation ( R ) of
5354 0.15 shall replace the figure produced by the coefficient of correlation formula in paragraph 1.
5355 4. For qualifying revolving retail exposures, as set out in Article 147(5A), a coefficient of correlation
5356 ( R ) of 0.04 shall replace the figure produced by the coefficient of correlation formula in paragraph
5357 1.
5358 4A. An institution shall increase the total risk-weighted exposure amounts calculated under
5359 paragraphs 1, 3 and 4 for retail exposures to reflect:
5360 (a) any post model adjustments in respect of risk-weighted exposure amounts calculated under
5361 point (b) of Article 146(3);
5362 (b) any amount needed to ensure that risk-weighted exposure amounts for non-defaulted
5363 exposures which are retail exposures secured by UK residential immovable property are
5364 greater than or equal to 10% of the exposure value for such exposures (following application
5365 of any post model adjustments calculated under point (b) of Article 146(3));
5366 (c) any unrecognised exposure adjustment calculated under Article 166D(6).
5368 5. For purchased retail receivables, R shall be calculated in accordance with the coefficient of
5369 correlation formula in paragraph 1.
5370 To be eligible for the retail treatment, purchased retail receivables shall comply with the
5371 requirements set out in Article 184 and meet the following conditions:
5372 (a) the institution has purchased the receivables from unrelated third party sellers, and its
5373 exposure to the obligor of the receivable does not include any exposures that are directly or
5374 indirectly originated by the institution itself;
5375 (b) the purchased receivables shall be generated on an arm’s-length basis between the seller
5376 and the obligor. As such, inter-company accounts receivables and receivables subject to
5377 contra-accounts between entities that buy and sell to each other are ineligible;
5379 Page 105 of 492